Overview
| Global production | Global producers | EU consumption | EU share | EU suppliers | Import reliance |
|---|---|---|---|---|---|
| 21,956,471t | Chile 25% Peru 11% Congo, D.R. 11% China 9% United States 5% Russia 4% Indonesia 4% Zambia 4% Australia 4% Mexico 4% | 1,647,857t | 8% | Poland 20% Brazil 12% Peru 10% Chile 10% Spain 7% Bulgaria 6% Indonesia 5% Sweden 4% Turkey 3% Panama 3% | 51% |
| Global production | Global producers | EU consumption | EU share | EU suppliers | Import reliance |
|---|---|---|---|---|---|
| 26,145,378t | China 44% Chile 8% Congo, D.R. 7% Japan 6% Russia 4% United States 4% Korea, South 2% Germany 2% Poland 2% India 2% | 2,906,739t | 11% | Germany 18% Poland 17% Belgium 11% Spain 10% Bulgaria 7% Chile 6% Russia 5% Sweden 5% Congo, D.R. 4% Austria 3% | 14% |
[
| Use | Percentage | Substitute | Sub share | Cost | Performance |
|---|---|---|---|---|---|
| Building construction, Electrical power | 20.8% | no substitute | 75% | No Substitute | No substitute |
| Building construction, Electrical power | 20.8% | Aluminium | 25% | Similar or lower costs | Reduced |
| Building construction, Electrical power | 20.8% | no substitute - alt: 50% | 0% | No substitute | |
| Building construction, Electrical power | 20.8% | Aluminium - alt: 50% | 0% | Similar or lower costs | Reduced |
| Building construction, Electrical power | 20.8% | Aluminium - alt: 22% | 0% | Reduced | |
| Manufacture, Transport, Automotive, Electrical | 11.2% | no substitute- Alt: 100% | 74% | No Substitute | No substitute |
| Manufacture, Transport, Automotive, Electrical | 11.2% | Aluminium | 13% | Similar or lower costs | Reduced |
| Manufacture, Transport, Automotive, Electrical | 11.2% | Aluminium | 13% | Similar or lower costs | Reduced |
| Manufacture, Industrial, non-electrical | 8.8% | no substitute - Alt: 75% | 56% | No Substitute | No substitute |
| Manufacture, Industrial, non-electrical | 8.8% | Plastics | 25% | Similar or lower costs | Reduced |
| Manufacture, Industrial, non-electrical | 8.8% | Steel | 19% | Similar | |
| Manufacture, Industrial, Electrical | 8% | no substitute | 74% | No Substitute | No substitute |
| Manufacture, Industrial, Electrical | 8% | Aluminium | 26% | Reduced | |
| Manufacture, Industrial, Electrical | 8% | Aluminium | 0% | Similar or lower costs | Reduced |
| Building construction, plumbing | 7.8% | no substitute | 75% | No Substitute | No substitute |
| Building construction, plumbing | 7.8% | Plastics | 25% | Similar or lower costs | Reduced |
| Building construction, plumbing | 7.8% | Plastics - alt: 6% | 0% | Similar | |
| Building construction, plumbing | 7.8% | Aluminium - alt: 7% | 0% | Similar | |
| Infrastructure, Power utility | 7.4% | Aluminium / Superconducting materials | 50% | ||
| Infrastructure, Power utility | 7.4% | no substitute | 50% | No substitute | |
| Infrastructure, Power utility | 7.4% | Aluminium - Alt: 14% | 0% | ||
| Infrastructure, Power utility | 7.4% | no substitute - Alt: 75% | 0% | No Substitute | No substitute |
| Infrastructure, Power utility | 7.4% | Aluminium - Alt:25% | 0% | Similar or lower costs | Reduced |
| Infrastructure, Power utility | 7.4% | Aluminium - alt: 50% | 0% | Similar or lower costs | Reduced |
| Infrastructure, Telecommunications | 2.9% | no substitute | 75% | No Substitute | No substitute |
| Infrastructure, Telecommunications | 2.9% | optical fibre | 25% | Slightly higher costs (up to 2 times) | Similar |
| Building construction, Architecture | 1.3% | different substitutes, such as tiles | 100% | Similar or lower costs | Similar |
| Building construction, Communications | 1.3% | no substitute | 75% | No Substitute | No substitute |
| Building construction, Communications | 1.3% | optical fibre | 25% | Slightly higher costs (up to 2 times) | Similar |
| Building construction, building plant | 0.5% | no substitute | 75% | No Substitute | No substitute |
| Building construction, building plant | 0.5% | Plastics | 25% | Similar or lower costs | Reduced |
Market analysis, trade and prices
| Global production | Global producers | EU consumption | EU share | EU suppliers | Import reliance |
|---|---|---|---|---|---|
| 21,956,471t | Chile 25% Peru 11% Congo, D.R. 11% China 9% United States 5% Russia 4% Indonesia 4% Zambia 4% Australia 4% Mexico 4% | 1,647,857t | 8% | Poland 20% Brazil 12% Peru 10% Chile 10% Spain 7% Bulgaria 6% Indonesia 5% Sweden 4% Turkey 3% Panama 3% | 51% |
| Global production | Global producers | EU consumption | EU share | EU suppliers | Import reliance |
|---|---|---|---|---|---|
| 26,145,378t | China 44% Chile 8% Congo, D.R. 7% Japan 6% Russia 4% United States 4% Korea, South 2% Germany 2% Poland 2% India 2% | 2,906,739t | 11% | Germany 18% Poland 17% Belgium 11% Spain 10% Bulgaria 7% Chile 6% Russia 5% Sweden 5% Congo, D.R. 4% Austria 3% | 14% |
The global market for primary copper is currently at approximately 21.5 million tonnes per year. With on average 26% of global mine production between 2019 and 2023, Chile is by far the largest mining country for copper worldwide. It is followed by Peru with 11% and Congo D.R. with 10%. The ten largest extraction countries provide almost 80% of global primary supply. The market for primary is relative diverse with countries from very different world regions. However, there is no EU country among the 10 largest copper mining countries.
With about 1.7 million tonnes per year, the EU consumes 8% of global mine production. 49% of European consumption is provided by mines from within the EU, 51% are imported. Imports originate mainly from the Latin American countries Brazil (12%), Chile (10%), Peru (9%).
Global production of refined (processed) copper was about 25.6 million tonnes per year between 2019 and 2023. China is the largest producer with a 42% share, followed by Chile with 9% and Japan and the DRC with 6% each. The ten largest processing countries produce 78% of refined copper. With Germany and Poland, there are two EU countries among the ten largest processers. Their shares correspond to 2% each.
The EU consumes about 2.9 million tonnes of refined copper per year. This corresponds to almost 12% of global production. With 14% import reliance for refined copper, the EU has a strong supply from within the region. Germany and Poland were mentioned above as two of the ten largest processing countries globally. The necessary imports come mainly from Russia, Chile and the DRC. It is important to note that results are an average of data for the years 2019-2023. Imports of refined copper from Russia decreased significantly in 2023.
| Mining | Processing/refining | ||
|---|---|---|---|
| CN Code | Title | CN Code | Title |
| 26030000 | Copper ores and concentrates | 74010000 | Copper mattes; cement copper 'precipitated copper' |
| 74020000 | Copper, unrefined; copper anodes for electrolytic refining | ||
| 74031100 | Copper, refined, in the form of cathodes and sections of cathodes | ||
| 74031300 | Copper, refined, in the form of billets | ||
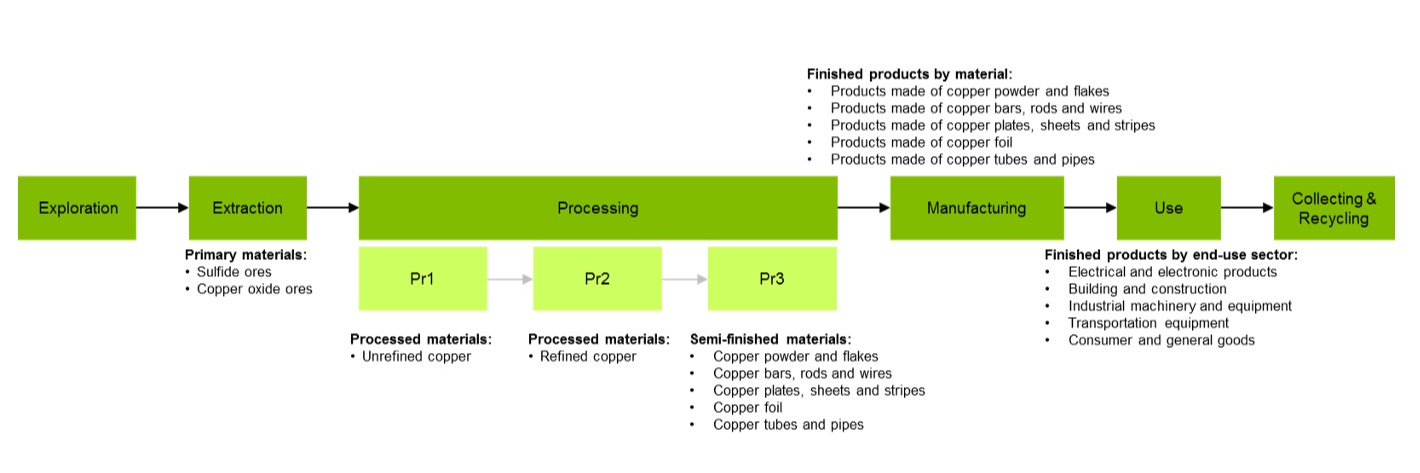
Table 6 gives an overview of the relevant trade codes for copper metal. CN code 26030000 contains the mine products copper ore and copper concentrate. The copper content is usually estimated to be around 30% but it varies in a broader range of 20-40%. Copper mattes and cement copper in CN 74010000 are already more concentrated with a copper content of 75%. The next step in the value chain (CN code 74020000) are copper anodes that are cast for electrolytic refining and contain often contain already >98% copper. However, the European Copper Institute defines anodes as intermediates above 80% copper content. After electrolytic refining, copper is traded mainly as cathodes and sometimes in the form of billets reported in CN codes 74031100 and 74031300, respectively. Copper cathodes have a copper concentration of >99.99% [ECI,2018] [ICA,2020] [Langner, B. E.,2011].
From the year 2000 onwards, imports of copper ores and concentrates were always significantly above exports. Imports grew steadily from 670 kilotonnes in 2000 to 1.2 million tonnes in 2014 (all numbers in Cu content). Since then import numbers have been quite stable around 1.2 million tonnes. Similarly, exports of ores and concentrates grew from 61 kilotonnes in 2000 to almost 410 kilotonnes in 2018. In recent years exports fluctuated between 280 and 390 kilotonnes.
Looking at countries of origin for imports of copper ores and concentrates to the European Union, a diversication process can be observed between the years 2000 and 2024. Back in 2000, Chile and Indonesia were by far the largest trade partners with 270 and 250 kilotonnes, respectively. The third largest portion is significantely smaller with 110 kilotonnes and comes from Rest of the World. Other listed countries are Turkey, the USA, Canada and Georgia with import volumes between 29 kilotonnes (Turkey) and below 1 kilotonne (Georgia). In 2024, the most important trade partners are Brazil, Peru, Chile and Indonesia with about 240 kilotonnes, 210 kilotonnes, 200 kilotonnes and 120 kilotonnes. In fourth position is Rest of the World with 130 kilotonnes. However, Turkey, Canada, Georgia, the USA and Marocco still export 78 - 9 kilotonnes to the EU. Therefore, the European Union currently has a quite diverse sourcing for copper ores and concentrates.
Compared to the imports of copper ores and concentrates, the imports of copper mattes and cement copper are low. This is also because mattes and cement are still relatively unpure intermediates that are in general traded to a lesser extent. Copper matte is the product of smelting before converting. Cement copper is produced from cementation of metallic copper from a copper sulfate solution [Langner, B. E.,2011]. Companies prefer to either import mine products directly and process themselves or import copper in later stages of the value chain. Import volumes are fluctuating strongly from around 30 kilotonnes between 2007 and 2011 to around 1 kilotonnes between 2013 and 2015 to again 23-28 kilotonnes between 2018 and 2020. Between 2021 and 2024, imports have been stable at around 13 kilotonnes per year. While mattes and cement copper used to come largely from Rest of the World, the countries of origin are now mainly Japan, Canada, Norway and Mexico. Exports of mattes and cement copper used to be below 10 kilotonnes before 2010. Between 2011 and 2019, exports were relatively stable between 20-30 kilotonnes before they increased significantly to about 48 kilotonnes in 2020. However, exports have come down again since to only aproximately 21 kilotonnes in 2024.
Copper anodes are imported more than mattes and cement but volumes are still low compared to ores and concentrates or refined copper cathodes. Between 2000 and 2011, there was an upwards trend in anode imports. Volumes increased from around 72 kt in 2000 to almost 180 kt in 2011. Since then, they decreased again to only about 49 kt in 2024. The largest supplier used to be Chile with 22 kt, followed by Zambia with 6 kt and Namibia with 4 kt out of the total 72 kt in the year 2000. Now, it is mostly Namibia with 36 kt and Chile with 11 kt of anodes they exported to the EU in 2024. Exports of anodes from the EU have been continiously below the import level and fluctuated between 5 kt and 80 kt. This maximum was reached in 2023 and 2024 when exports actually surpassed imports significantly for the first time.
Copper cathodes were imported in large amounts in the early 2000s. Until 2008, amounts of 1.5-1.8 million tonnes of copper were imported on a yearly basis to the EU. From 2009-2018, imports decreased spanning from 940 kilotonnes up to 1.2 million tonnes per year. Afterwards, imports dropped again to only 660-860 kilotonnes in recent years. In 2023, the lowest value of the entire timeframe was observed with 660 kilotonnes of cathode imports. In 2024, imports increased slightly to about 710 kilotonnes. The countries of origin were mostly the same in 2000 and 2024. However, 48% of cathodes came from Chile and another 33% from Russia in 2000. In 2024, Chile is still the most important trade partner but Russia dropped down to sixth place with a significant drop from 2022 to 2023 due to the trade restrictions against Russia. Russia's share in EU imports is now almost 5%. Second and third most important countries of origin were the DRC and Congo in 2024.
Exports of copper cathodes from the EU used to be at a very low level. In 2000, 130 kilotonnes were exported annually. They then increased and fluactuated around 500 kilotonnes between 2009 and 2020. Since then, they dropped again to around 220 kilotonnes in 2024.
Imports of refined copper in the form of billets is not really relevant at the scale of the overall value chain of copper in the European Union. For the last 20 years, imports have been below 5 kilotonnes only rising to 8 kilotonnes in 2023 and 6 kilotonnes in 2024. Almost all of those came from Vietnam. At the beginning of the century, they seem to have played a slightly larger role with a spike of 32 kilotonnes in 2002. However, they were imported from the United Kingdom which was an EU country back then. Exports used to be significantly higher than imports but still small compared to the copper value chain. Exports increased to almost 66 kilotonnes in 2004 and decreased again to about 6 kilotonnes in 2015. Exports stayed stable at this level until 2024.
Copper trading takes place predominantly in three commodity exchanges: The London Metal Exchange (LME), the Commodity Exchange Division of the New York Mercantile Exchange (COMEX/NYMEX) and the Shanghai Futures Exchange (SHFE). On the LME, copper is traded in 25 tonne lots and quoted in US dollars per tonne; on COMEX, copper is traded in lots of 25,000 pounds and quoted in US cents per pound; and on the SHFE, copper is traded in lots of 5 tonnes and quoted in Renminbi per tonne. More recently, mini contracts of smaller lots sizes have been introduced at the exchanges (ICSG, 2019a). The exchanges facilitate to hedge, store and to a limited degree also trade copper. The reference price refers to the cathode standard LME Grade A (≥ 99.99 % Cu). Copper is the industry metal that is considered being traded most intensly. In general, the copper price is determined by the copper supply and copper demand. In addition, speculative activities, exchange rates and market news about production losses have an impact on the price [DERA,2021] .
The annual average price of copper at LME differes significantely between year. The lowest price has been as low as 1460 USD / 1631 € per tonne of copper in 2001. With the strengthening of China as an emerging economic power, the copper price rose until the financial market crisis in 2008. The price managed to recover once the global economy recovered in 2009 and 2010. The highest price of the shown timeframe was observed in 2010 with 9650 USD / 7294 € per tonne of copper. After 2010, there was a general downwards trend in prices until 2015 where a price of 4706 USD / 4243 € was reached. This was due to due to previously built-up overcapacities and a decrease in GDP growth in China which ended in mid-2016. By the end of 2016, copper was trading at its lowest price in 7 years. The copper price experienced remarkable growth in 2017 due to a combination of supply and demand factors. The surge was largely due to structural changes implemented in the Chinese economy, which consumes around half of the global copper production. Production from the two largest copper mines was interrupted which tightened global supply. Furthermore, a decrease in the dollar index also supported global copper prices because a weaker US dollar makes copper more affordable with respect to other currencies
Copper demand is expected to significantly rise with the global push toward decarbonization, electrification and digitization on top of the general development of wealth and well-being that drives infrastructure and technology. The energy transition aiming for a substantial decrease in CO2 emissions in climate change mitigation needs copper in a multitude of ways (e.g., [Hund et al.,2020], [IEA ,2021], [Marscheider-Weidemann, F., et al.,2021]). For example, much more copper is needed for an electric vehicle than for an internal combustion engine-driven one, more resilient electric transmission becomes necessary, and large volumes of electricity storage facilities and electrolysis plants for hydrogen production need to be built (e.g., [Marscheider-Weidemann, F., et al.,2021]). In power generation, it is the wind power that demand most copper per MW produced, 3–6 times the demand in coal and natural gas power plants [IEA ,2021]. In terms of digitization, the need for copper from data centers is very relevant to keep in mind [Fastmarkets AI,2025].
Overall, [IEA ,2021] and [Marscheider-Weidemann, F., et al.,2021] forecast that, by 2040, the climate mitigation and other emerging technologies would need, depending on scenario, 20–40 % of the copper currently annually mined. A majority of this would go into building electricity transmission and distribution networks which is already today by far the largest application of copper. A forecast, by [S&P Global,2022] suggests that the demand of refined copper would roughly double by 2035 "with energy transition technologies accounting for about half of the growth in demand".
Obviously, recycling is not able to cover the demand gap due to continously rising demand and generally long lifetimes of copper products. Currently, end-of-life recycling (EoL RIR - end-of-life recycling input rate) covers about 16-17% of total world refined copper supply [ICSG,2025], [S&P Global,2022]. Also counting new scrap recycling, the recycling input rate is about 33% on global scale [ICSG,2025]. It is forecasted that recycling, even when increased as much as possible, could only cover an additional 5–10 % of the cumulative demand of copper by 2050, in a scenario where the global warming is kept at 2 degrees [Hund et al.,2020], [IEA ,2021], [S&P Global,2022]. This partially comes from the fact that copper does already have a well established recycling system and scrap that can be easily collected, processed and recycled is in many cases already being recycled. The EoL recycling rate is estimated to 39% on global level [ICSG,2025], comparatively high compared to many other metals. Low hanging fruits are already harvested. Increasing the recycling input further is therefore increasingly difficult but recycling rates show further potential.
Globally, the major issue is that there is not enough projected copper production to cover the demand in mid to long term [S&P Global,2022]. Investment in copper exploration is flat and the copper grade in new projects has been decreasing for decades, not showing any recent change. On the other hand, some see that a 'peak copper' won’t come anytime soon. [Singer, D.A.,2017] argued that “Demand for copper is not driven by time, but rather by population and per capita income. Rates of population increases are slowing and incomes in many countries are increasing. The per capita consumption of copper will increase over the coming years as populous nations such as China and India develop increasing per capita incomes, but that the demand will likely level off as their economies improve.” For example, [Dobra, J. & Dobra M.,2014], [Meinert, L.D. et al.,2016], and [Arndt, N.T. et al.,2017] agree with this view. The main issue that remains, is this: We know that there are very large resources but having in production all what is needed for the future demand in short to mid-term, at least, is uncertain. The [S&P Global,2022] report summarises: "While increasing mining capacity would certainly help close the supply gap, much would be required to lower the 16-year average that the IEA has estimated that it currently takes to move mining projects from discovery to production." Major projects exist in the pipeline but are constrained by?declining ore grades, increased resource nationalism, and long lead times (10-15 years). There are strategic projects in the EU that will increase domestic production in the future, e.g. the Skouries mine in Greece is expected to start production in mid 2026 and other projects exist in Spain, Finland and Norway. Reprocessing of mining and metallurgical waste has been discussed in the EU for its potential as valuable contribution to supply and solution to environmental issues. However, the economic side usually proves very difficult.
Demand
Copper is a metal with a very broad range of applications. Mostly used for its high electric and thermal conductivity but also its ductility, maleability, corrosion resistance and optics, copper is an essential part of energy generation and transmission, buildings, transportation, machinery, electronics and appliances, communication and even clothing, ammunition and coins. The International Copper Association estimates that 30.6 million tonnes of copper semi-finished goods were used by end-use production sectors in 2022 globally [ICA,2023]. For Europe, the available number for consumption is a little bit older but puts semis demand to 3.4 million tonnes in 2020 [ICA,2025]. Due to its central role as an electric conductor, copper plays an essential role in current trends of decarbonization, electrification and digitalization. Its demand will be driven strongly by the related technologies. However, copper is already a metal with a market used to huge volumes and very diverse uses. Even technologies with immense expected growth rates and significantely higher material intensities than conventional technologies such es electric vehicles or wind power plants will not change the entire copper market like it is happening for technology metals. Significant demand growth is expected though for copper globally and on European level across many scenario studies [IEA ,2021] [Marscheider-Weidemann et al.,2021] [Gregoir, L.; van Acker, K.,2022].
Figure 16 shows the relation between domestic production, imports and export which results in apparent consumption, here labled as demand, for the stage of copper extraction. Domestic production increased very slowly between 2000 and 2017 from 760 kilotonnes to 960 kilotonnes. Since then, domestic production decreased again slightly to about 780 kilotonnes in 2024. A stronger increase is observed for imports to the EU. They started almost level with domestic production in the early 2000s (670 kilotonnes in 2020) but increased significantely to 1.2 million tonnes in 2014. Since then, they have stayed at that level except for slight drops in 2016 and 2019. Exports, on the other hand, were almost insignificant during the first decade of the century, always staying below about 70 kilotonnes. Starting 2011, exports started to increase quickly to reach almost 410 kilotonnes in 2018. After a decrease in 2019 and 2020, volumes increased again to above 300 kilotonnes in 2022, 2023 and 2024.
All three put together gives an apparent consumption or demand that increases quickly from 1.4 million tonnes in 2000 to values between 1.7 and 1.8 million tonnes in 2005 where it stays for nine years until 2013. Between 2014 and 2017 apparent consumption increased slightly again to 1.8-1.9 million tonnes before dropping to 1.6 million tonnes in 2019. At first, consumption recovered again to almost 1.8 million tonnes in 2020 but declined since to 1.5 million tonnes in 2024.
Figure 17 shows the relation between domestic production, imports and export which results in apparent consumption, here labled as demand, for the stage of copper processing. Contrary to the extraction stage, domestic production is always above imports for the processing stage. It increases from 2.3 million tonnes to 2.7 million tonnes in 2012. Afterwards, production stays stable at values between 2.6 and 2.7 million tonnes.Only after 2020, demand numbers decreased again slightly to 2.4-2.5 million tonnes. Imports were in the range of 1.6-2.0 million tones between 2000 and 2008. Since then, they slowly decreased to only 780 kilotonnes in 2024. Exports were very low at only 190 kilotonnes in 2000 before rising to reach the range of 410-760 kilotonnes between 2009 and 2021.2022-2024 exports decreased slightly to 320-360 kilotonnes. All three result in an apparent consumption that started at 4 million tonnes in 2000 but decreased to 3.6 million tonnes in 2005. Consumption recovered to 4.1 million tonnes in 2006 but decreased even further to 3.0 million tonnes in 2013. Seemingly recovering again to 3.5 million tonnes in 2016, we observe a downward trend again in the years since, reaching the lowest value of the timeframe with 2.8 million tonnes in 2020 and stabilizing at around 3.0 million tonnes in the last few years.
Copper is crucial for several applications due to its unique properties. It is the best electrical conductor after silver and has very high thermal conductivity as well. Additionally, copper is corrosion resistant, ductile and malleable. These properties make copper into one main material for electrically conductive components in a wide variety of applications all the way from power generation to transmission and electricity consumers of all sizes. Besides electrical applications, copper is also used in various forms such as tubes, valves, fittings etc. in industrial machinery, building construction or the transport sector. Most copper is used in high purity coppers but a significant part of copper use is also in the form of alloys. Among the alloys, brasses - copper-zinc alloys - are the most important ones. Many other alloy combinations exist and are commonly used for specific applications. the importance of different uses is quite similar in the EU and on global scale. Plumbing, industry and automotive are slightly more important in the EU while power utility, cooling, electronic uses and consumer & general products have higher shares on global scale. This is directly connected to the structure of the manufacturing sector in the EU. While there is a strong industry for the production of industrial machinery and automotive in Europe, electronics and consumer goods are usually produced elsewhere in the world.
It is important to note that copper use undergoes a significant sectoral shift, globally but specifically also in the EU. While uses in construction stay important, the strong trend towards electrification drives copper use in all electrical and electronic uses. Green technologies like electric vehicles or wind turbines are very heavy in copper use. From a more general point of view, many appliances, tools, equipment and toys nowadays contain batteries, screens, lights and buttons and therefore copper. Maybe most important for copper, the electrification trend demands a significant expansion of the grid for transmission and distribution which is one of the main uses of copper.
Copper uses in Europe can be mostly correlated to six different NACE sectors: C26 - Manufacture of computer, electronic and optical products, C27 - Manufacture of electrical equipment, C28 - Manufacture of machinery and equipment n.e.c., C29 - Manufacture of motor vehicles, trailers and semi-trailers, C30 - Manufacture of other transport equipment and C32 - Other manufacturing. Out of those, C28 - Manufacture of machinery and equipment n.e.c. has been the most important one in terms of value added to the European economy. Starting at 175,000 M€ in 2000, C28 increased the value added to 260,000 M€ in 2022. More recent numbers are not available. Second most important is C29 - Manufacture of motor vehicles, trailers and semi-trailers which increased the value added from around 180,000 M€ in 2000 to 205,000 M€ in 2019. The other four sectors stay close to or below a threshold of 100,000 M€ reaching 100,100 M€ (C27 - Manufacture of electrical equipment), 71,500 M€ (C26 - Manufacture of computer, electronic and optical products), 73,997 M€ (C30 - Manufacture of other transport equipment) and 68,244 M€ (C32 - Other manufacturing) in 2022.
| Applications | 2-digit NACE sector | Value added of NACE 2 sector | 4-digit CPA |
|---|---|---|---|
| Building construction, Electrical power | C27 - Manufacture of electrical equipment | 125,000M€ | C27 - Manufacture of electrical equipment |
| Manufacture, Transport, Automotive, Electrical | C29 - Manufacture of motor vehicles, trailers and semi-trailers | 240,806M€ | C29 - Manufacture of motor vehicles, trailers and semi-trailers |
| Manufacture, other, diverse | C32 - Other manufacturing | 70,000M€ | C32 - Other manufacturing |
| Manufacture, Industrial, non-electrical | C28 - Manufacture of machinery and equipment n.e.c. | 280,306M€ | C28 - Manufacture of machinery and equipment n.e.c. |
| Manufacture, other, Consumer & general products | C32 - Other manufacturing | 70,000M€ | C32 - Other manufacturing |
| Manufacture, Industrial, Electrical | C27 - Manufacture of electrical equipment | 125,000M€ | C27 - Manufacture of electrical equipment |
| Building construction, plumbing | C28 - Manufacture of machinery and equipment n.e.c. | 280,306M€ | C28 - Manufacture of machinery and equipment n.e.c. |
| Infrastructure, Power utility | C27 - Manufacture of electrical equipment | 125,000M€ | C27 - Manufacture of electrical equipment |
| Manufacture, Transport, other transport | C30 - Manufacture of other transport equipment | 75,800M€ | C30 - Manufacture of other transport equipment |
| Manufacture, other, cooling | C28 - Manufacture of machinery and equipment n.e.c. | 280,306M€ | C28 - Manufacture of machinery and equipment n.e.c. |
| Infrastructure, Telecommunications | C27 - Manufacture of electrical equipment | 125,000M€ | C27 - Manufacture of electrical equipment |
| Manufacture, other, electronic | C26 - Manufacture of computer, electronic and optical products | 110,000M€ | C26 - Manufacture of computer, electronic and optical products |
| Building construction, Architecture | C28 - Manufacture of machinery and equipment n.e.c. | 280,306M€ | C28 - Manufacture of machinery and equipment n.e.c. |
| Building construction, Communications | C27 - Manufacture of electrical equipment | 125,000M€ | C27 - Manufacture of electrical equipment |
| Manufacture, Transport, Automotive, non-electrical | C29 - Manufacture of motor vehicles, trailers and semi-trailers | 240,806M€ | C29 - Manufacture of motor vehicles, trailers and semi-trailers |
| Building construction, building plant | C32 - Other manufacturing | 70,000M€ | C32 - Other manufacturing |
Copper is crucial for several applications due to its unique properties. It is the best electrical conductor after silver but much more price efficient. Additionally, copper is corrosion resistant, ductile and malleable. These properties make copper to one main material for electrically conductive components in a wide variety of applications.
Copper is used in many forms to connect buildings to the electricity network as well as distribute the electricity within the building. This includes of course the wiring of the building but also electrical outlets, switches and locks.
Copper is also a coinage metal and as such part of many coins. All types of European Euro and Euro Cent coins do contain copper in different alloys or as coating. Clothing has copper in buttons and zippers. Ammunition has copper in bullets, cartridges and shells.
Copper is corrosion resistan, antibacterial and impermeable and thus has been used in the production of water pipes for at least 4,500 years (ECI, 2016a).
Important copper-containing electrical parts in the automotive sector are the wire harness and all electronic systems from motor control, lights and anti-lock braking systems to window regulators, air conditioning and entertainment and navigation systems. On average, there are up to 25 kg of copper in a conventional car. With the switch to electric vehicles, this number will rise further. Both, the electric motor as well as the lithium ion battery contain relevant amounts of copper. Estimates give 40 kg of copper in a hybrid-electric vehicle, 60 kg in a plug-in hybrid electric vehicle and 83 kg in a battery electric vehicle (ECI, 2016a; ICA, 2017).
Copper and its alloys, mainly brass and bronze, are important raw materials for many kinds of mechanical parts such as valves, fittings, sleeve bearings and other forged parts (CDA, 2016). Copper is also needed for its high heat conductivity, e.g. in heat pumps or radiators.
Copper is contained in all consumer and general products that rely on electricity in any way or form. From ICT equipment and household appliances to instruments and tools, everything with a plug or a battery contains copper in wires and circuits. Copper is therefore an essential material in everyday life of consumers.
The power transmission and distribution networks rely in large parts on copper and its high electrical conductivity. While overhead lines are made of aluminum, all underground and sea cables contain a copper core. Further, building blocks such as transformers and converters also need copper.
Copper is due to its high electrical conductivity part of all electrical equipment and machinery, also for industrial uses. It is for example part of all industrial transformers and motors.
Not only cars but also other transport application such as trains, ships and planes do of course contain copper. All electric and electronic systems on board need copper in wiring and appliances. Additionally, there are non-electronic parts such as heat exchangers or tubes.
Due to its high thermal conductivity, copper is an essential material for heat exchangers. In that capacity, it is part of air conditioning and refrigeration systems.
Copper is used in telecommunication networks no matter if internet or telephony, fiber optics or wireless systems.
All industrial and commercial electronics and computers fall into this category. The copper is contained in printed circuit boards, wires and cables.
Copper is an essential part of the communication wiring of buildings.
Non-electrical parts are significantely less relevant compared to electrical applications of copper in automotive industry. Noteworthy are the radiator and some tubing that do contain copper.
Beside the electrical and water systems, copper is also used in buildings for the heating and cooling systems, e.g. in aircon tubes.
In architecture, copper is used for its functionality and architectural or optical characteristics. This includes copper for roofing, gutters or flashing but also for decorational parts.
| Use | Percentage | Substitute | Sub share | Cost | Performance |
|---|---|---|---|---|---|
| Building construction, Electrical power | 20.8% | no substitute | 75% | No Substitute | No substitute |
| Building construction, Electrical power | 20.8% | Aluminium | 25% | Similar or lower costs | Reduced |
| Building construction, Electrical power | 20.8% | no substitute - alt: 50% | 0% | No substitute | |
| Building construction, Electrical power | 20.8% | Aluminium - alt: 50% | 0% | Similar or lower costs | Reduced |
| Building construction, Electrical power | 20.8% | Aluminium - alt: 22% | 0% | Reduced | |
| Manufacture, Transport, Automotive, Electrical | 11.2% | no substitute- Alt: 100% | 74% | No Substitute | No substitute |
| Manufacture, Transport, Automotive, Electrical | 11.2% | Aluminium | 13% | Similar or lower costs | Reduced |
| Manufacture, Transport, Automotive, Electrical | 11.2% | Aluminium | 13% | Similar or lower costs | Reduced |
| Manufacture, Industrial, non-electrical | 8.8% | no substitute - Alt: 75% | 56% | No Substitute | No substitute |
| Manufacture, Industrial, non-electrical | 8.8% | Plastics | 25% | Similar or lower costs | Reduced |
| Manufacture, Industrial, non-electrical | 8.8% | Steel | 19% | Similar | |
| Manufacture, Industrial, Electrical | 8% | no substitute | 74% | No Substitute | No substitute |
| Manufacture, Industrial, Electrical | 8% | Aluminium | 26% | Reduced | |
| Manufacture, Industrial, Electrical | 8% | Aluminium | 0% | Similar or lower costs | Reduced |
| Building construction, plumbing | 7.8% | no substitute | 75% | No Substitute | No substitute |
| Building construction, plumbing | 7.8% | Plastics | 25% | Similar or lower costs | Reduced |
| Building construction, plumbing | 7.8% | Plastics - alt: 6% | 0% | Similar | |
| Building construction, plumbing | 7.8% | Aluminium - alt: 7% | 0% | Similar | |
| Infrastructure, Power utility | 7.4% | Aluminium / Superconducting materials | 50% | ||
| Infrastructure, Power utility | 7.4% | no substitute | 50% | No substitute | |
| Infrastructure, Power utility | 7.4% | Aluminium - Alt: 14% | 0% | ||
| Infrastructure, Power utility | 7.4% | no substitute - Alt: 75% | 0% | No Substitute | No substitute |
| Infrastructure, Power utility | 7.4% | Aluminium - Alt:25% | 0% | Similar or lower costs | Reduced |
| Infrastructure, Power utility | 7.4% | Aluminium - alt: 50% | 0% | Similar or lower costs | Reduced |
| Infrastructure, Telecommunications | 2.9% | no substitute | 75% | No Substitute | No substitute |
| Infrastructure, Telecommunications | 2.9% | optical fibre | 25% | Slightly higher costs (up to 2 times) | Similar |
| Building construction, Architecture | 1.3% | different substitutes, such as tiles | 100% | Similar or lower costs | Similar |
| Building construction, Communications | 1.3% | no substitute | 75% | No Substitute | No substitute |
| Building construction, Communications | 1.3% | optical fibre | 25% | Slightly higher costs (up to 2 times) | Similar |
| Building construction, building plant | 0.5% | no substitute | 75% | No Substitute | No substitute |
| Building construction, building plant | 0.5% | Plastics | 25% | Similar or lower costs | Reduced |
The unique properties of copper make it difficult to substitute it in various applications, especially due to its thermal and electrical conductivity. Nevertheless substitution options exist and are described in Table 8 and in more detail below (Glöser et al., 2013; BGS, 2007; USGS, 2019).
Aluminium can replace copper in electrical equipment like wiring or power cables though it is prone to conduction loss through corrosion. The performance is lower than in the case of copper. Aluminium has 61% of the conductivity, requiring a 56% larger cross-section for equivalent current carry. It can be more corrosion resistant but is also more susceptible to thermal creep and galvanic corrosion at connections, demanding specific alloys and termination techniques. The material costs are significantly reduced compared to copper. They can be offset by increased material demand and higher installation costs though. The balance between advantages and disadvantages of copper and aluminum therefore highly depend on the specifics of the project [DMA engineers,2020], [Smyrak, B et al,2021] [TME electronics,2026].
Silver has a higher electrical conductivity than copper, but comes with higher material costs. In North America, copper-clad aluminum wires are already on the market and being succesfully used in buildings. They do create a problem for recycling though since the copper-clad aluminum cannot easily be separated from common copper wires. Wire scrap is usually a sought-after high quality scrap that is efficiently remelted into new products without any refining steps that could remove the aluminum [Loibl, A., Tercero Espinoza, L.,2021].
It is estimated that 25% of the copper demand for electrical power uses in building construction could be substituted by aluminum. Building codes could be a restricting factor.
In other applications in the manufacturing sector, copper can currently not be substituted. There is no research available. However, the potential for successfull substitutions is estimated to be quite low.
Plastics and aluminium can replace approximately 25% of copper in plumbing applications, for example in water pipes, plumbing fixtures, and drain pipes (BGS, 2007). The costs are lower but the performance is also worse. Copper is much more durable the plastics for example in terms of temperature and pressure limits. Steel might also be a substitute in some cases. It comes with lower thermal conductivity and relatively high total costs though.
In electrical applications in the automotive sector, copper can currently not be substituted. However, the potential for successfull substitutions is estimated to be very low. Aluminum wiring might be an option that would also reduce weight but redesign and validation costs need to be considered.
It is estimated that one quarter of the copper used in non-electrical industrial applications can be substituted by plastic. For the other three quarter, no substitute material is available. Plastic has the advantage of being more cost effective. However, the performance is usually lower due to lower durability.
The substitutability of copper in consumer & general products has not yet been assessed in detail. However, it is assumed to be very low. There are no well-described substitutes known at the moment.
About 25% of copper in power utility applications can be substituted by aluminium. Aluminium is cheaper but also has a lower performance. Due to the lower conductivity a higher crosssection is needed for cables. Therefore, more material is often necessary counteracting the lower price. Additionally, installation can be more complex and thermal limits are lower for aluminum. For the other 75% of copper use in power utility applications, no substitute is known.
About 25% of copper in electrical industrial applications can be substituted by aluminium. Aluminium is cheaper but also has a lower performance with a lower conductivity and less corrosion resistency. Redesign of machines might also be necessary increasing engineering costs. For the other 75% of copper use, no substitutes are available.
No substitute is known for copper in other applications in the transport sector.
The substitution of copper in cooling has not yet been well assessed. It is assumed that substitutability is low. However, aluminum is lighter and less cost intensive and therefore potentially a substitute for applications with lower thermal conductivity needs such as automotive radiators. Stainless steel is another option. Redesign can actually lead to very good results for heat exchange but reparability and corrosion resistance stay an issue.
Supply
About 1 million tonnes of copper contained in concentrates were annually produced in EU during the period 2016-2020. Poland, Spain, Bulgaria, and Sweden are the main producers at the production stage (Eurostat, 2021). The EU refinery production of copper in the same year was 2,654,800 tons; of that, 24 % was produced in Germany, 21 % in Poland, 15 % in Spain, 12 % in Belgium, and the rest (28 %) in Austria, Bulgaria, Finland, Italy, and Sweden (Iodine et al. 2022). EU imported 4.95 million tonnes of copper under various forms including: concentrates with 30% Cu concentration, copper mattes with 75% Cu content and metallic Cu. The majority of copper amount is imported by Chile, Peru and Brazil. At the same period 1.6 million tonnes of various copper products (including concentrates, mattes and metallic copper) were extracted to third countries. China, Namibia and Turkey are the major partners. The copper recycling rate in EU is estimated at 17%, however this value is not updated and it is referred in the period 2012-2016 (Eurostat, 2021).
The final products from smelting and refining (copper cathodes) in EU are made through electrolytic processes. These are either sold directly into the market, or melted and cast into shapes, typically referred to as billets and cakes, for easier processing by downstream users (ECI, 2016b). Further downstream in the EU, many companies operate in the semi-fabricated products sector. About 80 companies, employing some 35,000 people throughout the EU-28, produce copper and copper alloy rods, bars, wires, sections, tubes, sheet and strip. Around 30 companies have integrated foundries, for the in-house production of cakes, billets and other shapes while the others purchase their requirements on the merchant market (ECI, 2016b).
Several countries have restrictions concerning trade with copper ores and concentrated (OECD, 2016). According to the OECD´s inventory on export restrictions, Indonesia and Mongolia show export taxes bigger than 25%. Further countries with export taxes on ores and concentrates are Zambia (15%), China (10%), Democratic Republic of Congo (DRC) (10%), and Argentina (10%). Several of these countries also require a licensing agreement. Indonesia has shifted its export tax in 2012 several times (even prohibited exports temporarily), only to remove restrictions afterwards. Indonesia has issued an export ban for a couple of months in 2014, with partial lifts of the bans after that time. Less countries have restrictions in place concerning trade with refined copper: China, Russia and DRC apply export taxes below 25% on refined copper, of which only China and Russia exported to the EU in the period 2012-2016. There is also a wide range of other countries imposing trade restrictions on products with a high percentage of copper content.
The simplified material system analysis available from the EU is for the year 2014 and therefore quite old [Passarini et al.,2018]. A newer Sankey diagram is available from the International Copper Association for the year 2020 [ICA,2025]. It is still covering EU28, but so is the MSA by the EU considering it is covering the year 2014. When comparing the two, one can observe that the general picture for the European copper cycle is still valid. Domestic extraction is still in the same range. Primary material imports are significantly lower at about 1.2 million tonnes in 2020. Exports on the same level decreased as well to around 300 kilotonnes. Secondary material is now primarily imported rather than exported by the EU (570 kilotonnes imported, 280 kilotonnes exported). This change can be directly related to the import ban of waste and scrap by China. 710 kilotonnes of processed copper were imported while 520 kilotonnes of copper were exported. Imports of processed copper therefore decreased but not as significantly as exports did. Imports of copper in products were at 1.9 million tonnes with 260 kilotonnes imported as semi-finished and 1.7 million tonnes as end-use products. Exports were at 1.6 million tonnes with 600 kilotonnes in semi-finished and 1.0 million tonnes in end-use products. The addition to the in-use stock of copper is estimated to be 410 kilotonnes in 2020. Recycling increased to almost 1.8 million tonnes of copper in 2020. This leaves 1.1 million tonnes of copper in EoL products not observed in recycling streams and therefore e.g. lost to landfill or unreported trade. Losses in the value chain were estimated to 420 kilotonnes with the majority occuring in scrap separation processes. In-use dissipation together with copper abandoned in place is estimated to be 140 kilotonnes in 2020.
Most of the copper is produced as the main product from copper mines. In addition, a significant amount of copper comes as a co-product from zinc, lead, nickel, and gold mines, and in minor volumes as a by-product from gold, silver, and molybdenum mines.
The presence of copper in the earth’s crust ranks it as a moderately present element, with 28 parts per million (ppm) upper crustal abundance [Rudnick & Gao,2014]. Copper combines with numerous elements so more than 150 copper minerals have been identified. The most important minerals for copper extraction are chalcopyrite (CuFeS2) and chalcocite (Cu2S). Further relevant copper minerals are chrysocolla (Cu4H4[(OH)8|Si4O10] · nH2O) and malachite (Cu2[(OH)2|CO3]). Copper is one of the few metals that in some cases occur in nature in a directly usable metallic form, i.e., as native metal. Copper deposits are found worldwide in a variety of geological environments. Hydrothermal deposits are most significant on a global scale, although magmatic and supergene deposits are locally important. The porphyry copper deposits are currently the world’s main source of copper (50–60% of world production), with copper grades generally from 0.2 % to >1 % [Bide, T.,2007]. Globally significant deposits are known from occur in Canada, Chile, China, Indonesia, Peru, Philippines, and Papua New Guinea; within the EU, large porphyry copper deposits are known from Bulgaria, Greece, Hungary, Romania, and Sweden. Sediment-hosted deposits, mainly located in the Central African Copperbelt, but also, e.g., in Poland and Germany, are the world’s second most important source of copper (about 20 % of current world production), grading about 1–2 % copper. In the entire Europe, the Polish sediment-hosted deposits are the largest source of mined copper [WMD,2022], [PGI,2017-2022]. Volcanogenic massive sulphide (VMS) deposits are also important sources of copper, with grades at 0.1–3 % copper [Bide, T.,2007]. Large Cu-rich VMS deposits currently mined within the EU include Cobre Las Cruces (Spain), Neves Corvo (Portugal), and Kristineberg (Sweden). Within the EU, copper is also produced from black shales (Terrafame, Finland), ultramafic-hosted nickel deposits (Kevitsa, Finland), and epithermal gold-silver deposits (e.g., Chelopech, Bulgaria).
| Country | Resources (tonnes) |
|---|---|
| World Resources | 2,100,000,000 |
The world identified resources of copper in 2015 were about 2,100,000,000 tonnes, 1,500,000,000 tonnes of unextracted copper and 600,000,000 tonnes of past production [USGS,2026]. Additionally, assumed ("undiscovered") resources of 3,500,000,000 tonnes are assumed jointly in porphyry and sediment-hosted types, and 850,000,000 t Cu in other deposit types [USGS,2015]. Not yet taken into account are the amounts of copper found in deep sea nodules and land-based and submarine massive sulphides [ICSG,2026]. Some copper is typically recovered as a by-product or co-product, especially from nickel, zinc, molybdenum, silver and gold ores which also demonstrates that world resources of the metal are not fully indicative of available supplies.
| Country | Resources (tonnes) |
|---|---|
| Australia | 100,000,000 |
| Canada | 7,000,000 |
| Chile | 180,000,000 |
| China | 41,000,000 |
| Congo | 80,000 |
| India | 2,200,000 |
| Indonesia | 21,000,000 |
| Kazakhstan | 20,000,000 |
| Mexico | 53,000,000 |
| Peru | 85,000,000 |
| Poland | 33,000,000 |
| Russia | 80,000,000 |
| United States of America | 47,000,000 |
| Zambia | 21,000,000 |
| Other countries | 210,000,000 |
| World total | 980,000,000 |
According to [USGS,2026], the world known reserves of copper (metal content) are about 980,000,000 tonnes and are quite diversified. The largest reserves are currently identified in Chile (180 Mt, 18%), Australia (100 Mt, 10%), Peru (85 Mt, 9%) and Russia (80 Mt, 8%). The small shares of even the largest contributing countries show, that copper has a diversified list of reserves.
| Country | Classification | Quantity (Mt of ore) | Grade (% Copper) | Reporting code | Reporting date | Deposit, Source | ||
|---|---|---|---|---|---|---|---|---|
| Bulgaria | Measured | 7.0 | 0.96 | NI43-101 | 03/2022 | Chelopech mine [Dundee,2022] | ||
| Bulgaria | Indicated | 6.8 | 0.82 | NI43-101 | 03/2022 | Chelopech mine [Dundee,2022] | ||
| Bulgaria | Inferred | 2.9 | 0.82 | NI43-101 | 03/2022 | Chelopech mine [Dundee,2022] | ||
| Bulgaria | All resources (3) | 143 | 0.43 | Historic | 2013 | Assarel mine [Mudd, G.M. & Jowitt, S.M.,2018] | ||
| Bulgaria | All resources (3) | 244 | 0.37 | Historic | 2013 | Medet mine [Mudd, G.M. & Jowitt, S.M.,2018] | ||
| Bulgaria | All resources (3) | 350 | 0.39 | Historic | 2013 | Elasite mine [Mudd, G.M. & Jowitt, S.M.,2018] | ||
| Cyprus | Inferred | 9.5 | 0.65 | JORC | 2020 | Magellan mine project [Venus Minerals,2020] | ||
| Cyprus | All resources | 15 | 3.8 | Historic | 2006 | Mavrovouni [Mudd, G.M. & Jowitt, S.M.,2018] | ||
| Finland | Measured + indicated + inferred | 932.8 | 0.14 | JORC | 12/2020 | Terrafame mine [Mineral Deposit Database of Finland ,2022] | ||
| Finland | Measured | 50.0 | 0.33 | PERC | 12/2021 | Kevitsa mine [Boliden A,2022] | ||
| Finland | Indicated | 88.0 | 0.36 | PERC | 12/2021 | Kevitsa mine [Boliden A,2022] | ||
| Finland | Inferred | 0.2 | 0.19 | PERC | 12/2021 | Kevitsa mine [Boliden A,2022] | ||
| Finland | Indicated | 3.5 | 3.45 | NI43-101 | 2017 | Sakatti mine project [Anglo American,2017] | ||
| Finland | Inferred | 40.9 | 1.77 | NI43-101 | 2017 | Sakatti mine project [Anglo American,2017] | ||
| Finland | Measured | 38.197 | 0.161 | NI43-101 | 2007 | Ahmavaara mine project [Puritch, E. et al.,2007] | ||
| Finland | Indicated | 114.816 | 0.181 | NI43-101 | 2007 | Ahmavaara mine project [Puritch, E. et al.,2007] | ||
| Finland | Inferred | 34.757 | 0.17 | NI43-101 | 2007 | Ahmavaara mine project [Puritch, E. et al.,2007] | ||
| Finland | Measured + indicated + inferred | 6.84 | 0.39 | PERC | 12/2019 | Kylylahti closed mine | ||
| Finland | Measured + indicated + inferred | 12.7 | 0.17 | JORC | 09/2022 | Hautalampi mine project | ||
| Finland | Measured | 26.031 | 0.1 | NI43-101 | 2007 | Konttijärvi mine project | ||
| Finland | Indicated | 37.571 | 0.095 | NI43-101 | 2007 | Konttijärvi mine project | ||
| Finland | Inferred | 11.638 | 0.097 | NI43-101 | 2007 | Konttijärvi mine project | ||
| Finland | Measured + indicated + inferred | 221 | 0.17 | NI43-101 | 01/2014 | Hannukainen mine project | ||
| Finland | Indicated + inferred | 43 | 0.19 | NI43-101 | 01/2014 | Kuervitikko deposit | ||
| Finland | Indicated + inferred | 32.0 | 0.2 | NI43-101 | 2011 | Vaaralampi deposit | ||
| Finland | Indicated + inferred | 43.575 | 0.13 | NI43-101 | 09/2021 | Haukiaho deposit | ||
| France | All resources | 100 | 0.6 | Historic | 2006 | Rouez deposit | ||
| Germany | Indicated | 115.195 | 1.47 | NI43-101 | 5/2011 | KSL mine project | ||
| Germany | Inferred | 14.468 | 1.46 | NI43-101 | 5/2011 | KSL mine project | ||
| Greece | Measured (2) | 90.714 | 0.51 | NI43-101 | 9/2021 | Skouris mine project | ||
| Greece | Indicated (2) | 149.260 | 0.44 | NI43-101 | 9/2021 | Skouris mine project | ||
| Greece | Inferred | 67.657 | 0.40 | NI43-101 | 9/2021 | Skouris mine project | ||
| Hungary | All resources | 159 | 1.14 | Historic | 2013 | Recsk deposit | ||
| Ireland | Indicated | 2.656 | 0.3 | NI43-101 | 1/2019 | Kilbricken deposit | ||
| Ireland | Inferred | 1.681 | 0.2 | NI43-101 | 1/2019 | Kilbricken deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 169.551 | 1.93 | Polish standard | 12/2021 | Bytom Odrzanski deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 276.951 | 1.73 | Polish standard | 12/2021 | Glogów deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 0.608 | 0.82 | Polish standard | 12/2021 | Lubin-Malomice mine | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 233.176 | 1.97 | Polish standard | 12/2021 | Mozów deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 848.481 | 1.25 | Polish standard | 12/2021 | Nowa Sól deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 17.476 | 0.78 | Polish standard | 12/2021 | Radwanice-Gaworzyce mine | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 339.019 | 1.54 | Polish standard | 12/2021 | Retkow deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 0.232. | 1.72 | Polish standard | 12/2021 | Runa mine | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 0.199 | 2.01 | Polish standard | 12/2021 | Sieroszowice mine | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 296.043 | 1.91 | Polish standard | 12/2021 | Sulmierzyce Pólnoc deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 76.688 | 1.66 | Polish standard | 12/2021 | Zary deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 2.205 | 1.36 | Polish standard | 12/2021 | Niecka Grodziecka deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 23.651 | 0.70 | Polish stadard | 12/2021 | Nowy Kosciól deposit | ||
| Poland (1) | C2 + D + 'Anticipated subeconomic' categories | 49.890 | 1.2 | Polish standard | 12/2021 | Wartowice deposit | ||
| Portugal | Measured (2) | 8.985 | 3.6 | NI43-101 | 6/2021 | Neves-Corvo mine | ||
| Portugal | Indicated (2) | 51.023 | 2.1 | NI43-101 | 6/2021 | Neves-Corvo mine | ||
| Portugal | Inferred | 12.681 | 1.8 | NI43-101 | 6/2021 | Semblana deposit | ||
| Portugal | Measured + indicated | 14.378 | 0.38 | NI43-101 | 6/2021 | Lagoa Salgada mine project | ||
| Portugal | Inferred | 13.329 | 0.29 | NI43-101 | 6/2021 | Lagoa-Salgada mineproject | ||
| Romania | Measured (2) | 62.2 | 0.21 | NI43-101 | 4/2021 | Colnic & Rovina mine projects | ||
| Romania | Indicated (2) | 175.6 | 0.15 | NI43-101 | 4/2021 | Colnic & Rovina mine projects | ||
| Romania | Measured | 28.5 | 0.16 | NI43-101 | 2/2019 | Ciresata mine project | ||
| Romania | Indicated | 125.9 | 0.15 | NI43-101 | 2/2019 | Ciresata mine project | ||
| Romania | All resources | 355 | 0.50 | Historic | 2008 | Bucium-Tarnita deposit | ||
| Romania | All resources | 500 | 0.35 | Historic | 2013 | Moldova Noua deposit | ||
| Romania | All resources | 431 | 0.55 | Historic | 2013 | Rosia Poieni deposit | ||
| Romania | All resources | 150 | 0.35 | Historic | 2013 | Talagiu deposit | ||
| Romania | All resources | 100 | 0.25 | Historic | 2008 | Valea Morii deposit | ||
| Slovakia | All resources | 29 | 1 | Historic | 2006 | Bubietova-Orsblie deposit | ||
| Spain | Measured | 18.32 | 1.27 | JORC | 12/2021 | Las Cruces mine, primary sulphide | ||
| Spain | Indicated | 17.92 | 1.24 | JORC | 12/2021 | Las Cruces mine, primary sulphide | ||
| Spain | Inferred | 7.09 | 1.23 | JORC | 12/2021 | Las Cruces mine, primary sulphide | ||
| Spain | Indicated stockpiles | 5.0 | 1.19 | JORC | 12/2021 | Las Cruces mine, primary sulphide | ||
| Spain | Measured | 0.86 | 6.23 | JORC | 12/2021 | Las Cruces mine, secondary sulphide | ||
| Spain | Indicated | 0.06 | 2.51 | JORC | 12/2021 | Las Cruces mine, secondary sulphide | ||
| Spain | Inferred | 10.66 | 0.45 | NI43-101 | 2022 | Lomero-Poyatos deposit | ||
| Spain | Measured | 4.767 | 0.59 | NI43-101 | 9/2021 | El Valle mine | ||
| Spain | Indicated | 5.572 | 0.37 | NI43-101 | 9/2021 | El Valle mine | ||
| Spain | Inferred | 3.684 | 0.46 | NI43-101 | 9/2021 | El Valle mine | ||
| Spain | Measured | 152.1 | 0.39 | NI43-101 | 6/2018 | Riotinto mine project | ||
| Spain | Indicated | 106.1 | 0.40 | NI43-101 | 6/2018 | Riotinto mine project | ||
| Spain | Inferred | 18.1 | 0.50 | NI43-101 | 6/2018 | Riotinto mine project | ||
| Spain | Indicated | 7.76 | 0.66 | NI43-101 | 10/2017 | Alconchel deposit | ||
| Spain | Inferred | 15.03 | 0.47 | NI43-101 | 10/2017 | Alconchel deposit | ||
| Spain | Measured | 69.258 | 0.42 | NI43-101 | 4/2018 | Touro mine project | ||
| Spain | Indicated | 60.592 | 0.36 | NI43-101 | 4/2018 | Touro mine project | ||
| Spain | Inferred | 46.521 | 0.37 | NI43-101 | 4/2018 | Touro mine project | ||
| Spain | Measured (2) + indicated (2) + inferred | 147.2 | 1.4 | JORC | 7/2022 | MATSA mine project | ||
| Spain | Indicated + inferred | 73.4 | 0.61 | NI43-101 | 3/2022 | Masa Valverde mine project | ||
| Spain | All resources | 71 | 0.34 | Historic | 2013 | Aznacollar mine project | ||
| Sweden | Measured | 281 | 0.15 | JORC | 12/2021 | Aitik mine | ||
| Sweden | Indicated | 621 | 0.17 | JORC | 12/2021 | Aitik mine | ||
| Sweden | Inferred | 15 | 0.19 | JORC | 12/2021 | Aitik mine | ||
| Sweden | Measured | 0.17 | 0.8 | JORC | 12/2021 | Kristineberg mine | ||
| Sweden | Indicated | 3.9 | 0.6 | JORC | 12/2021 | Kristineberg mine | ||
| Sweden | Inferred | 8.1 | 0.8 | JORC | 12/2021 | Kristineberg mine | ||
| Sweden | Indicated | 0.36 | 1.6 | JORC | 12/2021 | Petiknäs N deposit | ||
| Sweden | Inferred | 0.17 | 0.9 | JORC | 12/2021 | Petiknäs N deposit | ||
| Sweden | Indicated | 0.8 | 2.1 | JORC | 12/2021 | Rockliden deposit | ||
| Sweden | Inferred | 9.2 | 1.7 | JORC | 12/2021 | Rockliden deposit | ||
| Sweden | Indicated | 1.5 | 0.5 | JORC | 12/2021 | Renström mine | ||
| Sweden | Inferred | 0.93 | 0.5 | JORC | 12/2021 | Renström mine | ||
| Sweden | Measured | 0.07 | 0.03 | JORC | 12/2021 | Garpenberg mine | ||
| Sweden | Indicated | 30.5 | 0.06 | JORC | 12/2021 | Garpenberg mine | ||
| Sweden | Inferred | 48.4 | 0.06 | JORC | 12/2021 | Garpenberg mine | ||
| Sweden | Measured | 1.1 | 0.20 | JORC | 12/2021 | Laver deposit | ||
| Sweden | Indicated | 512.4 | 0.22 | JORC | 12/2021 | Laver deposit | ||
| Sweden | Inferred | 550.6 | 0.21 | JORC | 12/2021 | Laver deposit | ||
| Sweden | Indicated | 12.7 | 1.5 | JORC | 12/2021 | Nautanen deposit | ||
| Sweden | Inferred | 8.7 | 1.4 | JORC | 12/2021 | Nautanen deposit | ||
| Sweden | All resources | 26.1 | 0.77 | NI43-101 | 2018 | Dingelvik deposit | ||
| Sweden | Measured | 3.526 | 2.2 | NI43-101 | 6/2021 | Zinkgruvan mine | ||
| Sweden | Indicated | 0.486 | 2.0 | NI43-101 | 6/2021 | Zinkgruvan mine | ||
| Sweden | Inferred | 0.217 | 1.7 | NI43-101 | 6/2021 | Zinkgruvan mine | ||
| Sweden | All resources | 3062 | 0.012 | NI43-101 | 2019 | Myrviken deposit | ||
| Sweden | All resources | 7.5 | 1.97 | Historic | 1992 | Adakfältet closed mine | ||
| Sweden | All resources | 45 | 0.25 | Historic | 1992 | Tallberg closed mine | ||
| Sweden | All resources (three ore bodies) | 52.4 | 1.0 | JORC | 2016 | Viscaria mine project | ||
| 1) Copper grade (%) calculated from ore and contained metal tonnage | ||||||||
| 2) Inclusive mineral reserves | ||||||||
| 3) The figures are not recent, and the remaining resources may be even significantly less now | ||||||||
The EU known copper resources are about 70-71 million tonnes (Mt) and reserves 26.5 Mt of copper. These are a meagre 3.5 and 3.0 % of the global known resources and reserves, respectively.
The largest copper reserve and resource in Europe is in the Kupferschiefer deposits (sediment-hosted Cu) in southern Poland and SE Germany. The Polish Kupferschiefer deposits cover about 52 % of the known EU resources and 76 % of the reserves. By deposit type, porphyry copper deposits contain 25 % of the EU resources and 13 % of the reserves, and VMS deposits 14 % of resources and 4 % of the reserves. Hence, very little of the total is covered for the other types of copper deposits. Among copper reserves per individual mines, the four largest are in Poland, and for the resources, the six largest deposits are in Poland, too. The largest porphyry-type deposit is the Aitik mine in Sweden, which is 5th largest reserve and 13th largest resource in the EU. Resources larger than that for Aitik (i.e., >1.5 Mt of copper), but smaller in total copper endowment (Aitik total is 4.3 Mt Cu), i.e., without any reported reserve, include the Bucium-Tarnita, Moldova Noua, Rosia Poieni (Romania), Laver (Sweden), and Recsk (Hungary) porphyry type, KSL (Germany) Kupferschiefer type, and the MATSA (Spain) VMS deposits. These have a resource at 1.7–2.4 Mt Cu. The Skouries porphyry copper deposit in Greece and the black shale hosted Terrafame mine in Finland also go into this 2 Mt copper endowment category with 0.87 Mt and 0.74 Mt in reserves plus additional 1.4 Mt and 1.3 Mt in resources, respectively.
There also is a major potential for additional copper resources in all regions with active and closed copper mines and/or unexploited resources. For Finland, such "undiscovered" resources have been estimated at 50 % probability to contain 9,700,000 tons (9.7 Mt) of copper [Rasilainen, K., et al.,2017]. We have no knowledge of similar modern, numerical, estimates been done elsewhere in the EU. However, one should assume an "undiscovered" copper endowment of similar size, if not larger than that for Finland, also for Bulgaria, Poland, Portugal, Romania, Spain, and Sweden. Smaller additional endowment probably is, at least, in Cyprus, Czechia, France, Germany, Greece, Hungary, Ireland, Italy, and Slovakia. An additional caveat for the data comes from the fact that public updated information, or any resource information at all, seems to be missing for several deposits in, at least, Bulgaria, Germany, Hungary, Italy, and Romania. Especially stressing the issue is for Bulgaria, Hungary, and Romania where there is a significant potential for large porphyry-type deposits and wherefrom the public data for known deposits is old.
| Country | Classification | Quantity (Mt of ore) | Grade (% Copper) | Reporting code | Reporting date | Source | ||
|---|---|---|---|---|---|---|---|---|
| Bulgaria | Proven | 5.8 | 0.85 | NI43-101 | 3/2022 | Chelopech mine | ||
| Bulgaria | Probable | 13.6 | 0.78 | NI43-101 | 3/2022 | Chelopech mine | ||
| Finland | Proven + probable | 525.2 | 0.14 | JORC | 12/2020 | Terrafame mine | ||
| Finland | Proven | 72.0 | 0.31 | PERC | 12/2021 | Kevitsa mine | ||
| Finland | Probable | 52.0 | 0.33 | PERC | 12/2021 | Terrafame mine | ||
| Greece | Proven | 73.101 | 0.52 | NI43-101 | 9/2021 | Skouris mine project | ||
| Greece | Probable | 74.014 | 0.66 | NI43-101 | 9/2021 | Skouris mine project | ||
| Poland * | "Economic resources in place" | 241.862 | 2.45 | Polish standard | 12/2021 | Glogów Gleboki-Przemyslowy mine | ||
| Poland * | "Economic resources in place" | 323.075 | 1.25 | Polish standard | 12/2021 | Lubin-malomice mine | ||
| Poland * | "Economic resources in place" | 66.463 | 2.31 | Polish standard | 12/2021 | Polkowice mine | ||
| Poland * | "Economic resources in place" | 73.250 | 2.60 | Polish standard | 12/2021 | Radwanice-Gaworzyce mine | ||
| Poland * | "Economic resources in place" | 116.658 | 1.39 | Polish standard | 12/2021 | Retków deposit | ||
| Poland * | "Economic resources in place" | 209.576 | 1.63 | Polish standard | 12/2021 | Rudna mine | ||
| Poland * | "Economic resources in place" | 166.952 | 2.81 | Polish standard | 12/2021 | Sieroszowice mine | ||
| Poland * | "Economic resources in place" | 10.291 | 1.38 | Polish standard | 12/2021 | Niecka Grodziecka closed mine | ||
| Poland * | "Economic resources in place" | 5.705 | 0.93 | Polish standard | 12/2021 | Nowy Kosciól closed mine | ||
| Poland * | "Economic resources in place" | 46.712 | 1.64 | Polish standard | 12/2021 | Wartowice deposit | ||
| Portugal | Proven | 3.801 | 0.3 | NI43-101 | 6/2021 | Neves-Corvo mine | ||
| Portugal | Probable | 20.974 | 0.3 | NI43-101 | 6/2021 | Neves-Corvo mine | ||
| Romania | Proven | 48.28 | 0.20 | NI43-101 | 4/2021 | Colnic & Rovina mine projects | ||
| Romania | Probable | 85.11 | 0.13 | NI43-101 | 4/2021 | Colnic & Rovina mine projects | ||
| Spain | Proven + probable | 3.324 | 0.34 | NI43-101 | 9/2021 | El Valle mine | ||
| Spain | Proven | 56.769 | 0.44 | NI43-101 | 4/2018 | Touro mine project | ||
| Spain | Probable | 34.137 | 0.41 | NI43-101 | 4/2018 | Touro mine project | ||
| Spain | Proven + probable | 37.1 | 1.6 | JORC | 7/2022 | MATSA | ||
| Sweden | Proven | 154.0 | 0.19 | JORC | 12/2021 | Aitik mine | ||
| Sweden | Probable | 1153.0 | 0.22 | JORC | 12/2021 | Aitik mine | ||
| Sweden | Proven | 0.04 | 0.4 | JORC | 12/2021 | Kristineberg mine | ||
| Sweden | Probable | 4.4 | 0.8 | JORC | 12/2021 | Kristineberg mine | ||
| Sweden | Proven | 0.44 | 0.5 | JORC | 12/2021 | Renström mine | ||
| Sweden | Probable | 4.0 | 0.3 | JORC | 12/2021 | Renström mine | ||
| Sweden | Proven | 7.7 | 0.03 | JORC | 12/2021 | Garpenberg mine | ||
| Sweden | Probable | 86.0 | 0.05 | JORC | 12/2021 | Garpenberg mine | ||
| * Copper grade (%) calculated from ore and contained metal tonnage | ||||||||
As shown in Table 12, the EU has known copper reserves of about 26.5 Mt of copper. They sum up to 3 % of the global known reserves. The largest reserves are located in Poland and Finland.
Global mine production of copper between 2000 and 2025 showed an continous increase. In 2025, 22.9 million tons were mined globally. The largest global producer of copper ores, with a 24 % share in 2025, is Chile; the second, third and fourth largest copper miners were the Democratic Republic of Congo, Peru, and China at 14 %, 12 % and 8 %, respectively. Chile has been the largest copper miner for many decades. Production has been stable at above 5 Mt for more than 20 years now. The large production volumes of the DRC are a more recent development. In 2010, the DRC still produced less than 0.5 Mt of copper per year. Since then, production rose to 3.1 Mt in 2025 thereby making the DRC the second largest mining country for copper. There is no EU country among the largest ten mine production countries.
Copper is one of the most recycled of all metals. There are two basic recycling pathways. Copper or copper alloy products can be remelted without or with minimal removal of impurities into new semi-finished product. This is cost- and energy-efficient but can lead to accumulation of impurities in the copper. It is usually done by manufacturers of semi-finished copper products. Many brass products allow for a certain range of impurities and can therefore take high shares of scrap in their material input stream. The second pathway is secondary smelting and electrolytic refining which can be done separate or together with primary material. It provides secondary copper of the same quality as primary cathode production. Ideally, copper is remelted into new products that have lower purity needs until it collected too many impurities and therefore goes through the full smelting and refining process. In theory, the combination of these two recycling processes allows an endless loop without loss of quality for copper. In reality, there are of course at least minimal material losses attached to every process. Nonetheless, the technical processes are available to allow for very high recycling rates for copper. [Langner, B. E.,2011], [Loibl, A., Tercero Espinoza, L.,2021].
Similarly, there are two general sources of copper scrap. Copper scrap derives from metal discarded in semi-final products fabrication or finished product manufacturing processes (new or pre-consumer scrap) and end-of-life products (old, end-of-life (EoL) or post-consumer scrap). New scrap is usually cleaner, of known composition and not as dispersed in the economy. It can therefore be collected and recycled very easily and efficiently. New scrap is assumed to already be recycled and therefore provides little potential for further improvements. EoL scrap on the other hand is widely dispersed in the global economy since copper is used in a huge variety of different product. It often but not always comes with many impurities and needs effort in collection, dismanteling, separation and sorting. However, there is EoL scrap that provides high quality scrap such as cable scrap and even low quality scrap can be well recycled for copper via scrap smelting and refining. For the last years, there is a trend for EoL scrap to become more and more complex and therefore requiring more and more effort and energy in processing. This is caused by the continuing trends of electrification and miniaturization. Products are becoming smaller but at the same time more powerful requiring smaller but more complex building blocks that contain a more varied composition of elements. Despite the call for "design for recycling", this trend is expected to continue in the future making recycling harder.
The recycling input rate (RIR) measures the share of secondary input in overall copper use. It is estimated to be just above 30% in recent years. The International Copper Study Group shows the RIR fluctuating between 31 and 35% 2010-2024 [ICSG,2025]. The material flow analysis by the International Copper Association and Fraunhofer ISI estimate a 10-year average of 31% for 2011-2020. For 2020, amounts of copper remelted into new semi-finished products was estimated to 4.38 Mt globally. Additionally, 3.69 Mt were recycled via secondary smelting and refining. This means about 8 Mt of copper were recycled in 2020 on global scale. If one looks only at EoL scrap recycling, the share of secondary input to overall copper use goes down to 16% (EoL RIR 2011-2020). This shows that new scrap recycling has a very relavant share in overall recycling. EoL or post-consumer recycling does have further potential for recycling improvements though. The EoL recycling rate gives the share of recycled EoL scrap in theoretically available EoL scrap. It was estimated to be at around 39% (EoL RR 2011-2020).
In Europe, the secondary input for copper is traditionally higher than the global average. In 2020, about 920 kt of secondary copper were remelted into new products and 830 kt were recycled via smelting and refining. This adds up to a RIR for EU28 of about 47% and 1.75 million tonnes of copper recycled. If only EoL recycling input is counted the rate is still comparatively high at about 33% (EoL RIR 2020). The share of recycled EoL material in theoretically available EoL scrap (EoL RR) is estimated to be about 46% for EU28 in 2020 [ICA,2025]. Other studies estimate a RIR of 40% [Ciacci et al.,2020] or for 2014 an EoL RR of 61% (including scrap exports) and 28% (recycling in the EU excluding scrap exports) [Passarini et al.,2018]. The latter also concludes a share of 47% for scrap from domestic manufacturing (new scrap) and 37% for scrap from EoL products. The rest comes from scrap imports.
| MSA Flow | Value | ||
|---|---|---|---|
| EU Primary copper demand 2020 [ICA,2025] | 1860 kt | ||
| EU secondary copper production 2020 [ICA,2025] | 1750 kt | ||
| EU EoL recycling input 2020 [ICA,2025] | 1100 kt |
According to the material flow analysis by ICA and Fraunhofer, the end-of-life recycling input rate (EoL RIR) is 16% on global level (10-year average 2011-2020) and 31% on European level (in 2020) [ICSG,2025], [ICA,2025].
As mentioned above, new scrap is usually cleaner and of known origin and composition. Therefore, it is easier to collect, sort and recycle. With companies trying to work more and more resource- and cost-efficient, the potential to recycling from new scrap is limited and already used to a very high degree. The share of new scrap in total recycling in the EU28 was estimated to be about 37% in 2020 [ICA,2025]. On global level, it is estimated to about 50% (10-year average 2011-2020) [ICSG,2025].
Primary copper production starts with the extraction of copper-bearing ores. There are three main techniques for mining copper: open pit mining, underground mining and leaching operations (heap leaching, and to a minor extent also in-situ leaching). Open pit mining is the most common form and appropriate for low grade ores that are close to the surface (< 100 m). For example, the open pit copper mines at Bingham Canyon in Utah, USA, and Chuquicamata in Antofagasta, Chile, belong to the largest man-made excavations in the world. Underground mining is suitable for higher grade ores and carried out for example in the Lubin mine, Poland. With in-situ leaching a weak sulphuric acid leach solution is pumped through lower grade ore bodies to dissolve copper. This technique is used for example in the Mufulira mine (Mopani Copper Mines) in the Zambian Copperbelt.
Mined ores generally contain 0.5 to 3% copper. After the ore has been mined, it is crushed and ground followed by a concentration by flotation. The first phase in processing the ore is concentration which increases the copper content to 25 to 35%. This is carried out at the mine site, involving crushing and grinding, followed by physical processing and separation stages. In the following smelting process, copper is transformed into “matte” containing 50-70% copper. The conversion into pure copper is done using two techniques: pyrometallurgical processes (including smelting and electrolytic refining) and hydrometallurgical processes (including leaching, solvent extraction and electro-winning). In the hydrometallurgical route, copper is extracted from mainly low-grade oxide ores and also some sulphide ores, through leaching (solvent extraction) and electrowinning (SX-EW process). Both processes (pyrometallurgical and hydrometallurgical) produce refined copper cathodes as output [ICSG,2021] [Langner, B. E.,2011].
Other considerations
Copper is classified as a heavy metal (German Environment Agency, 2020; Tchounwou et al., 2022). Copper is a nutrient that is essential for many biochemical and physiological functions. In particular, it intervenes in some enzymatic reactions due to its ability to cycle between an oxidized Cu(II) and reduced state Cu(I). This property makes it also potentially toxic especially in case of excessive exposure (Tchounwou et al., 2014; Gaetke and Chow 2003). At high concentrations, copper is mainly toxic to aquatic organisms with long lasting effects (ECHA, 2022a; US EPA 2022), which is also reflected in the CLP (Classification, Labelling and Packaging) notifications.
In Europe, the ECHA reports that to humans, effects can be harmful if the substance is swallowed or can cause eyes irritations in case of contact. Moreover, copper is approved to be used as a biocidal active substance and is under assessment regarding the Endocrine Disrupting list (ECHA, 2022b). Regarding compounds of copper, the CLP regulation (N°1272/2008) also considers cuprous chloride, copper hydroxide, cuprous oxide and cupric oxide (INERIS, 2019). Finally, in 2017 after a proposal from ANSES (Agence nationale de sécurité sanitaire de l'alimentation, de l'environnement et du travail), the product “granulated copper; [particle length: from 0,9 mm to 6,0 mm; particle width: from 0,494 to 0,949 mm]” was added to the CLP regulation, again due to the aquatic chronic effects.
Human exposures to copper are mainly linked to anthropospheric activities such as smelting, mining, industrial activities, domestic waste emissions and application as fertilizers, sewage sludge, algicides, fungicides or molluscicides (Flemming and Trevors, 1989; Tchounwou et al., 2014).
The environmental impacts of copper production are well assessed, especially using life cycle assessment (LCA). Globally it could be said that from extraction to refining, copper production is highly energy intensive leading to relevant emissions of GHG (greenhouse gases). Water consumption is also important in the copper life cycle, moreover this life cycle occurs in countries where the water stress is relatively high (Chile or Peru for example). Some of the copper mines are open pit mines, leading to potentially high land use impacts.
However, impacts from copper extraction and copper production are site-specific and mainly depend on the type of mining (open pit vs. underground mining), the type of ores exploited (oxidized vs. sulphuric) as well as the grade of the exploited ore and the type of metal processing technology (pyrometallurgy vs hydrometallurgy) (Northey et al. 2012; Sanjuan-Delmás et al., 2022).
Based on the information available in some copper miners’ and producers’ sustainability reports, (Northey et al. 2012) assessed the environmental footprint of copper production regarding energy intensity, carbon footprint and water footprint. Their compiled results are the following:
-
Energy intensity range [10 GJ/t Cu to 70 GJ/t Cu] with an average of 22.2 GJ/t Cu;
-
GHG intensity range [1 t CO2 éq/t Cu to 9 t CO2 éq/t Cu] with an average of 2.6 t CO2 éq/t Cu
-
Large variations are due to the mined ore grade, the type of electricity and energy used at the mine site and at the processing site. The different methods used to declare GHGs emissions in such company reports could also explain these variations;
-
-
Water intensity range [~1 kL/t Cu to 350 kL/t Cu] with an average of 74 kL/t Cu
-
The variations are mainly due to the location of the mine sites and mainly to the climatic conditions (arid regions such as Australia vs temperate cool regions such as Canada).
-
These results could be compared with a similar study conducted ten years later, in which the authors compiled LCA results for the cumulative energy demand and the global warming impacts indicators while looking at different characteristics of the mine site and the process used to produce metallic copper (Sanjuan-Delmás et al., 2022).
|
Case study |
Country |
Ore grade (%Cu) |
Mining type |
Process |
Global warming (kg CO2 éq / t Cu) |
Cumulative energy demand (MJ / t Cu) |
|
1 |
Australia |
2 |
Not specified |
Hydrometallurgy |
6200 |
64 000 |
|
2 |
Chile |
0.71 |
Not specified |
Pyrometallurgy |
6000 |
Not specified |
|
3 |
Chile |
0.71 |
Not specified |
Hydrometallurgy |
4900 |
Not specified |
|
4 |
Australia |
0.1 |
In situ leaching |
In situ leaching |
4780 |
61 000 |
|
5 |
Sweden |
0.18 |
Open pit |
Pyrometallurgy |
4750 |
168 000 |
|
6 |
Australia |
3 |
Not specified |
Pyrometallurgy |
3300 |
33 000 |
|
7 |
China |
1.02 |
Not specified |
Hydrometallurgy |
1910 |
Not specified |
Source: Sanjuan-Delmás et al., 2022
Regarding impact categories other than climate change and cumulative energy demand, (Sanjuan-Delmás et al. 2022) found in their study (in the case of open pit mining and pyrometallurgy processes) that they are mainly driven using explosives and SO2 emissions occurring at the smelter (especially for the impacts relative to photochemical ozone formation and acidification).
The type of ore exploited has also a direct incidence on toxicity-related impact categories. Especially, the tailings associated to sulfidic deposits could have long-term effects on the natural emissions linked to acid mine drainage and the increase of heavy metals concentration in the environment if the tailings are poorly managed in the long-term. Depending on the assessed mine site, these impacts can vary from several CTUe / kg Cu to more than 104 CTUe / kg Cu regarding ecotoxicity impacts (Adrianto et al., 2022).
According to the German Environment Agency, almost 85% of copper ores mined are sulfidic ores leading to high pre-conditions for acid mine drainage, subsequently leading to potential environmental harms near these mine sites. The Agency also reports copper deposits where low exposure to radioactive elements can occur, more particularly in China, the United States and the Democratic Republic of Congo (German Environment Agency, 2020).
The US EPA recently proposed the “National emission standards for hazardous air pollutants: primary copper smelting residual risk and technology review and primary copper smelting area source technology review” (EPA 2022). This proposal presents the results of the US EPA residual Risk and Technology Review (RTR) for the National Emission Standards for Hazardous Air Pollutants (NESHAP) for major source Primary Copper Smelters as required under the Clean Air Act. The EPA is proposing new emissions standards and to remove exemptions for periods of startup, shutdown, and malfunction (US EPA 2022b).
In addition, the Copper Mark – an association which group copper producers from all over the world – developed two Standards to set common expectations for responsible production practices. The first one is the Copper Mark criteria for responsible production, which uses the risk readiness assessment of the Copper I as the basis to evaluate the performance of the participants. The second one is the Joint due diligence standard for copper, lead, nickel and zinc – which implementation is currently voluntary and is planned to become mandatory for Copper Mark members (Copper Mark 2022).
The International Copper Alliance developed a set of indicators to link the UN SDGs and the GRI Standards with regards to copper production in relation to CO2 equivalent emissions, energy intensity, water recycled and reused, total workforce, injury rate, the economic value distributed and the sustainability reporting (ICA 2022).
The copper processing industry is a significant employer. On a global scale, the copper industry employs more than one million people and brings an added value of $144 bn to the global economy. (ICA, 2022). In the EU, many companies operate in the semi-fabricated products sector. The European Copper Institute represents an industry of €45 billion turnover and 50,000 jobs. (Metalsforbuilding, 2019).
Table 14 illustrates the high importance of copper exports are economically for many countries (Source: (COMTRADE 2022), based on data from 2020). They represent more than 50 % of the total export values for Zambia (74 %), DRC (57 %) and Chile (52 %), and more than 20 % for Namibia, Peru, Mongolia, Armenia and Georgia. Many other countries generate considerably more than 1 % of their export value from copper exports.
| Country | Export value (USD) | Share in total exports |
|---|---|---|
| Zambia | 5,776,737,637 | 74.02 |
| DR Congo | 8,117,466,745 | 57.48 |
| Chile | 38,363,000,000 | 51.78 |
| Namibia | 1,611,591,241 | 28.78 |
| Peru | 11,066,000,000 | 28.58 |
| Mongolia | 1,837,321,308 | 24.25 |
| Armenia | 559,867,777 | 24.01 |
| Georgia | 781,169,277 | 23.36 |
| Lao People's DR | 641,736,382 | 12.62 |
| Kazakhstan | 3,863,887,016 | 8.23 |
| Bulgaria | 2,496,153,679 | 7.82 |
| Mauritania | 215,806,510 | 7.63 |
| Myanmar | 924,829,443 | 5.46 |
| Usbekistan | 571,760,897 | 4.31 |
| Panama | 252,068,091 | 2.91 |
| Philippines | 1,641,306,832 | 2.52 |
| Australia | 5,570,001,281 | 2.27 |
| Indonesia | 3,633,519,341 | 2.23 |
| Serbia | 433,196,428 | 2.22 |
| Finland | 1,204,539,730 | 1.84 |
| Ecuador | 322,738,888 | 1.59 |
| Russian Federation | 5,202,508,152 | 1.54 |
| Brazil | 2,537,546,298 | 1.21 |
| Canada | 4,436,043,064 | 1.14 |
| Tadjikistan | 7,655,234 | 1.07 |
Strikes of workers occasionally occur especially in Latin America, where some of the largest copper mines are located. The reasons are not only related to the mining business, but sometimes rooted deep in societal inequality (Jamasmie, 2019). For example, the Escondida mine, was hit in 2018 by the longest private sector mining strike in Chile (44-days). In addition, mines in Chile can also be affected by strikes in ports like in October 2019 when a strike in Escondida mine was superposed by strikes at various sea ports handling copper concentrates (including Iquique, Tocopilla, Antofagasta and Ventanas) (Bloomberg, 2019).
Within Europe, the price spikes after 2000 have infamously created theft of copper objects from the public space. Thieves stole copper parts and then sold the valuable scrap metal to recyclers. The lack of these copper objects then caused disruptions of infrastructure, in particular overhead contact lines of electricity driven trains, trams and trolleybuses, but also power cables. Similarly, copper claddings were stolen from public and non-public buildings (Europol 2018).
In 2020, ICA announced the creation of the “Copper Mark”, a global standard to ensure responsible production and trading of copper inspired by the United Nations Sustainable Development Goals. ICA announced that “The new measure seeks to monitor the performance of copper mines and refineries around the globe, assessed against responsible production criteria. Unlike other sustainability programs currently in place, the Mark targets copper specifically. As such, there is hope that it will lay the foundations for the ethical development of an industry so crucial in the creation of a green future.” (ICA 2020)
The DELVE database reports that artisanal mining of copper ores can occur in the Democratic Republic of Congo. Despite the lack of official statistics, (Gerig et al. 2019) report that 10,000 tons of copper ore were extracted from artisanal production in two provinces in 2 months in 2019. Artisanal mining of copper also occurs in India (Lahiri-Dutt and McQuilken, 2019) as well as in Peru (where copper artisanal mining is linked to international copper prices) (Faulkner, 2019).
Copper-based flow batteries for energy storage renewables integration – CUBER project (EU, 2022 –2023)
The search for competitive energy storage is linked to the transition towards renewable energy solutions. The all-copper redox flow battery (CuRFB), based on RFB technology, is designed in a simple, modular, and scalable way and offers security and sustainability. The EU-funded CUBER project will prove that RFB technology can be integrated into Smart Cities and residential self-consumption market segments. Its development could allow more comprehensive applications, such as backup power systems in isolated areas, for energy management and grid balancing in renewable energy plants. The project coordinates a wide range of European actors to develop operating pilots to confirm and introduce innovative methods to produce and consume renewable energy in urban, rural, and industrial sites.
Surface-functionalised nanocrystal catalysts for the electrochemical reduction of carbon dioxide – SURFCAT (EU, 2020 –2022)
Among the crucial ways to reduce atmospheric CO2 is its capture and catalytic conversion into valuable chemicals. The electrochemical reduction of CO2 can help us store excess renewable electricity in the bonds of carbon-based liquid fuels and industrially relevant chemicals. It is a win-win-win proposition, reducing CO2, generating useful chemicals, and relying on renewable energy sources. However, it faces challenges related to the low selectivity, activity, and stability of electrocatalysts in aqueous solutions. The EU-funded SURFCAT project is developing approaches to modify copper nanocrystals, the catalyst of choice, to surpass these obstacles and spur the commercialisation of this important process to close the carbon cycle, protect the environment and provide fuels and chemicals.
Industrial Selective PLAting for Solar Heterojunction – iSPLASH (EU, 2022 –2024)
Despite the boom in the photovoltaics industry, there are still barriers to solar cell deployment. Costly and cumbersome manufacturing processes emitting high levels of greenhouse gas GHG constitute a significant hindrance. A critical step in cell manufacture is metallisation, representing over 30% of the cost of manufacture. Currently, heterojunction cell metallisation utilises silver paste, which has significant disadvantages in terms of price, efficiency, and environmental impact. Alternative metals, such as copper, can overcome these challenges; however, efficient process technology has not yet been brought to market. The iSPLASH project will cause a paradigm shift in heterojunction cell metallisation. Our technology will be the only processing technology on the market to cost-effectively exploit the low price of copper and facilitate the reliable and precise fine-line deposition of copper onto HJT cells, eliminating the use of silver. iSPLASH technology will reduce metallisation costs by 90% and carbon emissions.
TOMACOP: Copper homeostasis and the effects of copper deficiency on tomato plants and fruit quality (2019-2021)
Copper (Cu) is a vital micronutrient but is toxic when in excess. In humans, Cu is acquired by diet. Plants are also sensitive to Cu bioavailability in soil and their nutritional deficiencies or excesses are transferred to consumers. Therefore, deciphering the regulatory mechanisms underlying Cu uptake and distribution to edible products is crucial to prevent deficient or toxic Cu levels in horticultural crops that may ultimately affect human health. Furthermore, in Europe, around 20 % of the arable land is classified as Cu deficient, which has been compensated by using Cu-enriched fertilizers. However, the EU warns that this practice implies high environmental costs and compromises food security for consumers. TOMACOP studied the effects of Cu deficiency on plant growth and development and on fruit nutritional status and quality by using tomato (Solanum lycopersicum), one of the most important crops worldwide. The characterization of Cu homeostasis components and the identification of tissue-specificities in the molecular mechanisms regulating Cu uptake provided important clues for future biotechnological improvements aimed to solve the challenge EU agriculture is facing.
Mapping China's copper cycle from 1950–2015: Role of international trade and secondary resources (Hao et al, 2023)
China's high copper demands and poor mineral endowments have led it to rely heavily on the international copper trade. However, the importance of the metal trade has not been adequately appreciated. This study explores the role of metal trade in copper security through a high-resolution material flow analysis of China's copper cycle from 1950 to 2015 that covers over 300 types of copper-containing products. We found that the annual inflow of copper has increased from 4.3 KT/yr to 14 MMT/yr from 1950 to 2015, which drove the increase of copper stocks accumulated in buildings, infrastructures, and products from 7 kg/cap to 56 kg/cap. The total copper in-use stocks in China were approximately 80 MMT in 2015. However, about 70% of all copper used in China in this period was imported from other nations. Thus, this study indicates that more attention should be paid to the importance of the copper waste trade in China.